As infrastructure improves and economic activity deepens, residential prices across 11 emerging Tier-2 real estate markets, including Goa, Lucknow, Nagpur, Visakhapatnam and Coimbatore, have risen 63% over the past five years, compared with 42% growth across the top eight cities. Average residential prices in these markets range from ₹4,500 to ₹13,500 per sq ft, according to a report by CII-Knight Frank India released on September 18.
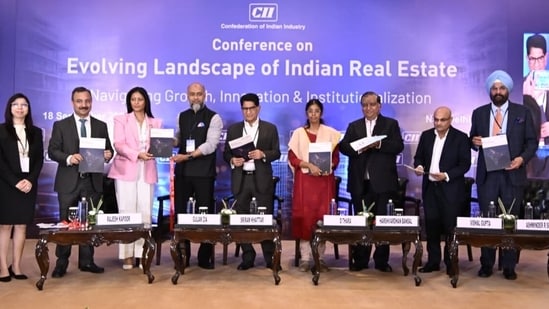
The report, titled ‘India’s Next Real Estate Markets’, noted that housing prices across the 11 emerging Tier-2 cities — Bhopal, Bhubaneswar, Chandigarh Tricity, Goa, Indore, Jaipur, Kochi, Lucknow, Nagpur, Visakhapatnam and Coimbatore — recorded an average compound annual growth rate (CAGR) of 8% between 2016 and 2026, compared with 4% across the top eight cities: Mumbai, Bengaluru, Delhi-NCR, Hyderabad, Chennai, Pune, Ahmedabad and Kolkata.
The report was released at the CII Real Estate Conference held in the capital on September 18.
The 11 Tier-2 cities are recording faster residential price growth than India’s top eight cities, indicating stronger momentum as their economic fundamentals improve, supported by growth in infrastructure, connectivity and consumption, the report noted.
"The gap has widened over the past five years, with residential prices across these 11 markets increasing by 63 % between 2021 and 2026, as compared to 42% growth across the top 8 cities," Knight Frank said.
While the top eight cities will continue to anchor the sector by volume, Tier-2 and Tier-3 cities are emerging as increasingly important growth centres. The report attributed this momentum to strengthening economic fundamentals, infrastructure development, improved connectivity and rising consumption.
Tier-2 buyers move towards integrated, amenity-led housing post-Covid
The CII-Knight Frank report noted that the pandemic and the resulting adoption of hybrid working altered consumer expectations of housing. It said that post-Covid changes in household finances and hybrid working increased flexibility over residential locations. Buyers in Tier 2 cities are increasingly moving from standalone buildings and conventional housing formats towards integrated, amenity-led communities.Residential demand is also differentiated by the economic role of each city, the report showed, adding Tier 2 and Tier 3 markets are not simply replicating metropolitan markets. A technology and services .centre may see demand concentrated around employment corridors, an industrial city may develop housing around manufacturing clusters, while a tourism market is likely to see demand for premium homes and second residences, the report noted.
India’s real estate sector output is projected to reach $5.8 trillion by 2047, with Tier-2 and Tier-3 cities estimated to contribute 25–30%, or $1.4–1.7 trillion. Realising this opportunity will require infrastructure that generates employment and enterprise, supported by demand-led formal supply, serviced land, efficient approvals, reliable utilities and liveable urban conditions, it said.
Commercial activity is also expanding across these markets. Tier-2 cities recorded 11.2 million sq ft of warehousing leasing in 2025, with six of the identified emerging markets accounting for 5.3 million sq ft. Meanwhile, 24 Tier-2 cities accounted for 36 million sq ft of India’s 134 million sq ft organised shopping-centre stock in 2025, the report said.
Shishir Baijal, international partner, chairman and managing director, Knight Frank India, said, “India’s real estate growth is increasingly broadening beyond the traditional metropolitan centres. The investable opportunity across Tier-2 and Tier-3 cities, satellite markets and emerging corridors will be shaped not simply by infrastructure creation, but also by their ability to convert connectivity into sustained economic activity.
“Cities that bring together employment, enterprise, population growth, consumption and urban capacity will be better placed to build deeper and more diversified real estate markets. For investors and developers, this represents a wider opportunity landscape, but one that requires greater selectivity and a sharper understanding of each market’s underlying economic drivers," he added.