The Unified Payments Interface (UPI) was launched in India in April 2016 with 21 members banks. The objective was to make digital payments as easy and hassle-free, instant and accessible for the citizens 24X7. Ten years later, UPI is presenting a significant achievement of India’s financial and digital transformation. It is an interoperable bank-to-bank real time payment system, linked with multiple bank accounts through a single mobile application of any specific bank account of user. This is the world’s largest digital payment system, with monthly transaction values reaching nearly 70% of the total currency in circulation. The UPI’s annual transaction value expanded from ₹0.07 lakh crores to ₹314 lakh crores. It has recorded more than 4000 times increase between the time frame 2016 to 2026. The scale of this transformation is remarkable and in 2024, UPI presented 49% volume of global realtime payment transactions.
In July 2026, UPI processed 23.66 billion transactions with total transaction value of approximately ₹29.88 lakh crore. The number of banks associated with UPI platform is 741. It has become an important digital rail through which a significant part of India's everyday economic activity takes place.
Ten Years of a Digital Payment Revolution
UPI changed the way Indians interact with their bank accounts. Instead of depending on account numbers, cards or complex banking procedures, users can make payments through a UPI ID, QR code, mobile number or other supported interfaces. The
transaction takes place directly through the banking system. Now there is no need for banks to be opened, remembering IFSC Codes, bank account details etc. of person to whom the money is being transferred.
The core feature of UPI is interoperability. Users of different banks and payment applications can transact with one another through common UPI infrastructure. Rather than creating a single closed payment platform, India established common digital rails on which banks, fintech companies and technology providers could build an inclusive financial ecosystem. The combination of public infrastructure and private innovation has created a landmark success story of UPI. The growth trajectory of UPI is illustrating the transformation of financial ecosystem of India. In April 2026, UPI processed approximately 22.35 billion transactions worth ₹29.03 lakh crore. In May, volume increased to 23.20 billion transactions, valued at around ₹29.90 lakh crore. By July, transaction volume had reached 23.66 billion transactions, while value stood at nearly ₹30 lakh crore.
{{/usCountry}}The core feature of UPI is interoperability. Users of different banks and payment applications can transact with one another through common UPI infrastructure. Rather than creating a single closed payment platform, India established common digital rails on which banks, fintech companies and technology providers could build an inclusive financial ecosystem. The combination of public infrastructure and private innovation has created a landmark success story of UPI. The growth trajectory of UPI is illustrating the transformation of financial ecosystem of India. In April 2026, UPI processed approximately 22.35 billion transactions worth ₹29.03 lakh crore. In May, volume increased to 23.20 billion transactions, valued at around ₹29.90 lakh crore. By July, transaction volume had reached 23.66 billion transactions, while value stood at nearly ₹30 lakh crore.
{{/usCountry}}| Month | Live Banks | Volume (In Millions) | Value (In ₹ Crores) |
|---|---|---|---|
| April-2026 | 713 | 22,346.80 | ₹29,02,988.05 |
| May-2026 | 720 | 23,201.93 | ₹29,90,424.21 |
| June-2026 | 731 | 22,716.07 | ₹28,92,138.67 |
| July-2026 | 741 | 23,658.35 | ₹29,87,880.49 |
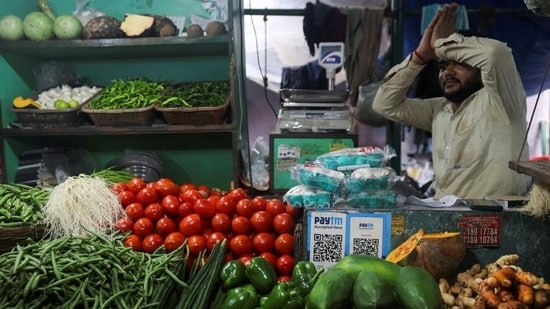
The QR code has become the most visible symbol of India's UPI revolution. From a small shopkeeper, street vendor, a hawker, tea seller, restaurant or local service provider can accept digital payments simply by displaying a QR code. This reduces the need for conventional point-of-sale infrastructure and allows even small-value transactions to move digitally.
The impact extends beyond convenience. UPI has lowered barriers for small businesses to participate in the formal digital economy. Consumers can use the same payment infrastructure to purchase groceries, pay utility bills, settle restaurant bills or transfer money to family members.
NPCI data illustrates the scale of this everyday usage. In August 2025, UPI processed 20.01 billion transactions worth ₹24.85 lakh crore. Person-to-merchant (P2M) transactions accounted for 12.71 billion transactions, while person-to-person (P2P) payments accounted for 7.30 billion. However, P2P payments represented the larger monetary value, at approximately ₹17.62 lakh crore, compared with ₹7.24 lakh crore for P2M transactions.
The PhonePe was most widely used UPI platform in August 2025, handling around 9.6 billion transactions, followed by Google Pay with 7.4 billion and Paytm with 1.6 billion. PhonePe also accounted for the largest share of transaction value at 48.64 per cent, compared with 35.53 per cent for Google Pay and around 8.5 per cent for Paytm. Other platforms such as Navi and CRED also recorded significant activity, with about 406 million and 219 million transactions, respectively. The figures show how UPI has created a highly competitive digital payments ecosystem, with several platforms serving India's rapidly growing base of digital users.
Also Read: 'This is false': Govt rejects 'foreign influence' charge in UPI merchant fee row
The importance of these platforms lies in the model behind them. Applications compete for users and merchants, while the underlying UPI infrastructure remains interoperable. This has created space for innovation in merchant payments, recurring payments, credit-linked products and other financial services without requiring each provider to establish an independent payment network.
UPI's growth has been supported by India's broader financial inclusion architecture. The expansion of bank accounts through Pradhan Mantri Jan-Dhan Yojana, Aadhaar-based identity infrastructure and widespread mobile connectivity created the foundations for a digitally connected financial eco-system. The UPI added the transaction layers successfully and created direct benefit transfer infrastructure for the beneficiaries.
From Domestic Success to Global Connectivity
After transforming domestic payments, UPI is increasingly moving beyond India's borders. The UPI Global Acceptance (International Merchant Payments) enables users to make QR-code-based payments at participating international merchant
locations directly from their Indian bank accounts through UPI-powered applications.
The process is designed to be familiar. Users first activate UPI Global/UPI International through a participating application. At an international merchant, they look for the BHIM UPI or participating network-partner acceptance logo, scan the merchant's QR code and review the payment details. The application can display the amount in both foreign and Indian currency, together with applicable exchange-rate or fee information. The customer then enters the UPI PIN to authorise the payment, after which both the customer and merchant receive confirmation. The UPI is working in 11 foreign countries for the UPI acceptance and cross-border remittances.
This simple interface conceals a complex cross-border payment infrastructure and demonstrates UPI's potential to connect India's financial system with international merchants.
The reverse flow is also emerging through UPI One World, which enables eligible international visitors to make merchant payments in India without requiring an Indian bank account or Indian mobile number. In 2026, NPCI extended the service to delegates from more than 40 countries attending the India AI Impact Summit.
Together, these initiatives demonstrate that UPI is evolving from a domestic payment system into an emerging platform for international digital payment connectivity.
A Decade That Changed How India Pays
Ten years after its launch, UPI has become much more than a payment interface. It is an important component of India's Digital Public Infrastructure (DPI), connecting banks, fintech companies, merchants and consumers through common digital rails.
Its journey from a 2016 innovation to more than 23 billion monthly transactions in 2026 demonstrates how interoperable infrastructure can reshape financial behaviour and expand participation in the digital economy.
UPI's story is ultimately a story of scale, inclusion and innovation. It has changed how India pays, lowered the barriers to digital commerce and created a foundation for new financial services. UPI has not only empowered rural India and poor by making them digitally savvy, it has also transformed the entire financial system.
As UPI expands internationally, its significance is becoming even broader. India's financial success story is increasingly becoming a story of digital connectivity—one in which infrastructure developed for a domestic population of more than 1.4 billion is beginning to connect people, merchants and economies across borders.
Ten years of UPI is therefore not simply the story of a successful payment system. It is a demonstration of how Digital Public Infrastructure can transform a financial system—and potentially help reshape the future of global digital payments.