India’s retail and wholesale inflation prints for August were largely on expected lines; at the cusp of 5% and 10% respectively. On a standalone basis, the inflation numbers are not too alarming. Most analysts see inflation for the September quarter as being only slightly higher than RBI’s current estimate of 4.7%.
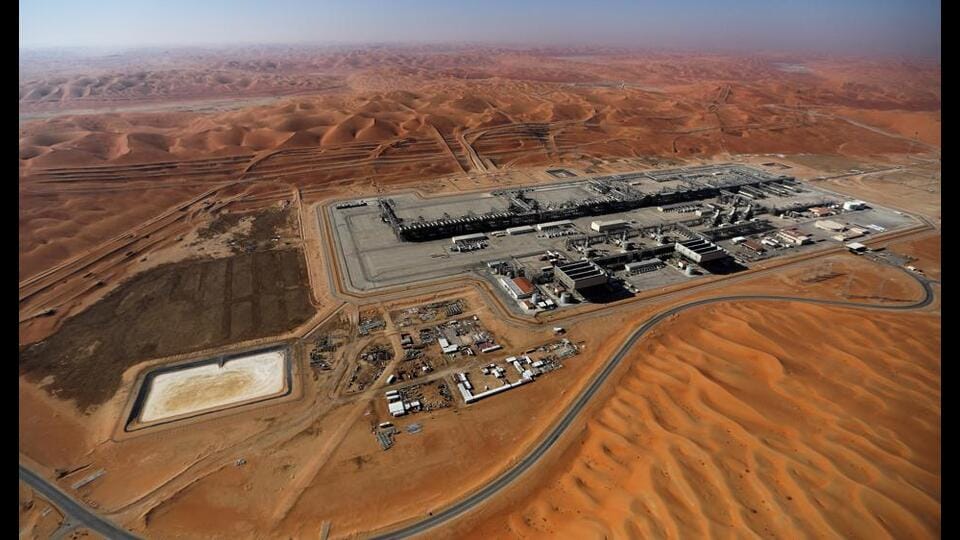
Crude oil prices, thanks to the rapid military advances by the Iran-backed Houthi rebels in Yemen along the Red Sea coast, have caused a major disruption to Saudi oil supplies. Brent crude, the international benchmark, is already above $100 per barrel. (Reuters)
However, the developments in the last couple of weeks should caution us against assuming a business-as-usual scenario. Crude oil prices, thanks to the rapid military advances by the Iran-backed Houthi rebels in Yemen along the Red Sea coast, have caused a major disruption to Saudi oil supplies. Brent crude, the international benchmark, is already above $100 per barrel. Its dated variants, a better indicator of the spot price, are trading even higher. Barring a resolution to the ongoing conflict in West Asia, we are looking at a prolonged disruption to the oil market.
As if an oil shock were not disruption enough, the most keenly watched interest rate in international markets, the 10-year yield on US treasuries, crossed the psychological threshold of 5% on Monday, for the first time after 2023. A Wall Street Journal commentary, appropriately pointed out that the 10-year yield had just gone below 4% in February when Donald Trump attacked Iran along with Israel in February. Rising oil on the back of already stubborn inflation, which is way above the Federal Reserve’s 2% target, will perhaps force the new Fed chairman Kevin Warsh to hike the interest rate in the US, even if it means going against the demands of Trump. Not raising rates would risk taking bond yields even higher.
What does all this mean for the Indian economy? First is the immediate question about inflation. Retail inflation, which is also the benchmark rate for RBI, might rise further if the government passes on the burden of higher fuel prices to consumers. So far, this has not happened. Not doing it long enough will entail a large fiscal cost. As inflation inches above and if the Federal Reserve too raises interest rates, RBI will face significant pressure to increase policy rates as well. Most analysts already see this happening, although they differ on the timing and magnitude of the hikes. These differences aside, the writing on the wall is clear: Brace for higher inflation and higher interest rates.
Unlock a world of Benefits with HT! From insightful newsletters to real-time news alerts and a personalized news feed – it's all here, just a click away! -Login Now!

 E-Paper



 Prefer HTon Google