
 E-Paper


Before India finalises its new steel policy, it has an opportunity to revisit its own green steel roadmap
Authors - Nandan Sharalaya, head of programme, Kinshu Dang, senior manager - networks and partnerships and Sakshi Balani, director, India at Climate Catalyst.

 Prefer HTon Google


Last week, the ministry of steel released the draft National Steel Policy: Vision 2047 (“Draft Policy”) for public consultation. The draft follows the ministry’s September 2024 publication of Greening the Steel Sector in India: Roadmap and Action Plan (“the Roadmap”), which set out a pathway for decarbonising India’s steel sector.
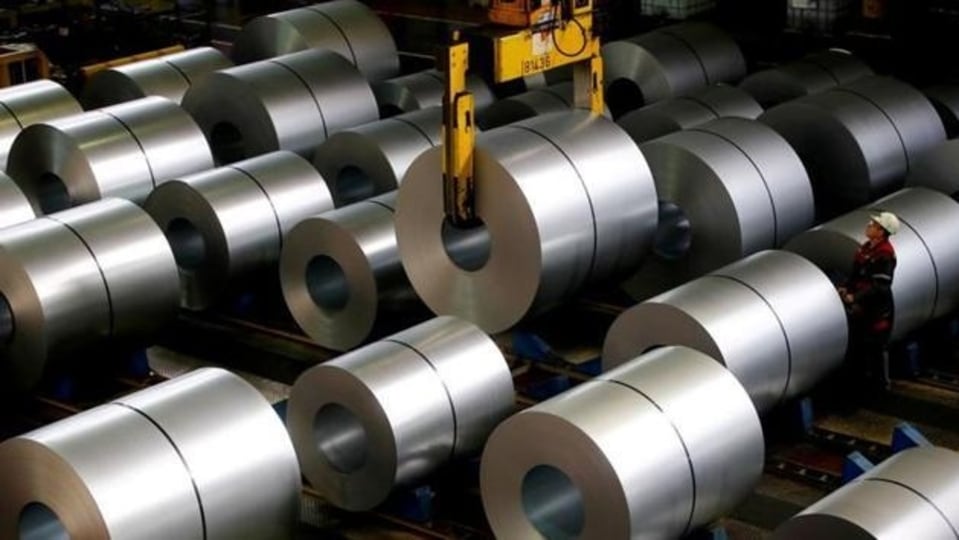
While the 2024 Roadmap asked how India could make steel with fewer emissions, the Draft Policy asks how India can make far more steel, securely and at low cost. In fact, it aims to triple crude steel capacity by 2047, from today’s 220 million tonnes per annum (MTPA). However, emissions reductions appear to have become a lower priority as the Draft Policy sets a less ambitious path for decarbonisation than the Roadmap.
This is most prominently reflected in the Draft Policy’s 2047 emissions-intensity target of 1.54 tCO₂/tcs (tonnes of CO₂ per tonne of crude steel). This target is close to the performance of the world’s most efficient blast furnaces today. In effect, this means that the target being set for 21 years from today, could be achieved simply through efficiency improvements, without deploying breakthrough technologies at scale or fundamentally changing how most of India’s steel is made.
Meanwhile, India’s steelmaking capacity is projected to nearly triple, from 220 MTPA today to around 600 MTPA by 2047. Despite a lower emissions intensity, annual emissions could rise from around 560 MtCO₂ to over 900 MtCO₂. A more efficient steel sector could still, in theory, produce significantly higher total emissions, making India’s 2070 net-zero target harder to achieve and requiring much steeper emissions cuts in the decades after 2047.
Since the Draft Policy is still open for consultation, there is an opportunity for the final version to incorporate ideas from the ministry’s own Roadmap. Four differences between the two documents stand out:
The Roadmap saw natural gas as the bridge to hydrogen and was openly cautious about coal gasification. This was due to its unsuitability for high-ash Indian coal and high capital costs, which have prevented it from scaling to commercial levels. The Draft Policy, by contrast, makes coal gasification a “lead lever” from 2030 to 2035, establishing it as a transition fuel to green hydrogen-based steelmaking.
On paper, coal gas looks like a sensible middle path, since India is reliant on imported natural gas but has plenty of domestic thermal coal. If shaft furnaces running on coal gas can blend in hydrogen over time and move the sector away from coal-based blast furnaces (BF-BOFs), it can be a viable transition option.
This needs far deeper scrutiny. Coal gasification plants add significantly to local air pollution in a country that is already suffering from the worst effects of pollution. They are also likely to cost more than gas-based ones. The method India’s large integrated plants follow to report emissions also leaves out methane from coal mines.
If coal gasification is to play a role, the final policy should require plants to incorporate carbon capture readiness into gasifier design, enable furnaces to blend green hydrogen, establish a clear timeline for each plant to phase out coal gas, and account for emissions from coal mine methane.
The Draft Policy assumes the blast furnace route rises from about 43% today to 55% by 2047. As per its own figures, blast furnace output grows from about 73 MT to 292 MT and coking coal demand from 72 MT to 236 MT. This would make it harder to meet the Draft Policy’s own goal of reducing dependence on imported coking coal. It also runs against the Roadmap’s warning that fossil plants built in the near term will run for at least 25 years and could end up stranded.
The Draft Policy expects blast furnaces to cut emissions later through reduced use of coal, improved efficiencies and carbon capture. While the Roadmap is bullish on the potential of carbon capture, the technology has an underwhelming track record and is yet to make economic sense on a steel plant anywhere in the world.
A safer approach would be to steer more new capacity toward technologies that can run on hydrogen and clean power.
Both documents expect large-scale hydrogen-based steelmaking to emerge in the 2030s, but differ on how quickly India should act. The Roadmap envisaged pilots before 2030 in blast furnaces, shaft furnaces and a fully hydrogen-based plant, backed by ₹455 crore ($47 million) under the National Green Hydrogen Mission. It also saw scope to blend hydrogen into existing furnaces as costs fell. The Draft Policy, however, assigns hydrogen no specific role until 2035-40 and does not mention the funded steel pilots.
Since the Roadmap was released two years ago, the economics of green hydrogen and its derivatives have improved. In 2025, SECI’s (Solar Energy Corporation of India Limited) green ammonia auctions discovered prices as low as ₹49.75/kg (52.31 US cents/kg), bringing green ammonia close to fossil-based alternatives. Green ammonia is produced using green hydrogen, and the prices discovered in these auctions provide an indication of the improving cost competitiveness of green hydrogen-based products against fossil-based alternatives. In October 2025, a SECI auction for 2 GW of solar paired with four hours of battery storage set a record-low tariff of ₹2.86/kWh (2.96 US cents/kWh). Cheaper renewable electricity and storage can help reduce the cost of producing green hydrogen, an important input for low-carbon steelmaking.
As a sunbelt economy, India has a natural advantage in renewable energy and competitive green hydrogen production. Delaying pilots and scale-up risks missing this opportunity. India should ensure funded green hydrogen Direct Reduced Iron (DRI) pilots begin before 2030 and explore a dedicated hydrogen auction for steel, modelled on SECI’s recent green ammonia auctions with 10-year offtake commitments that will help producers with the long-term demand certainty needed to develop the sector.
The Roadmap proposed developing a GPP framework by 2025 and establishing a bulk-buying agency for steel. The Draft Policy does not mention GPP, but proposes life-cycle costing in public tenders. GPP is a major opportunity for the government to create a lead market for low-carbon steel, providing producers with the demand certainty needed to invest in cleaner production.
Public projects across roads, railways, housing and defence account for over 25% of India’s steel demand, giving the government significant purchasing power. A CII-Climate Catalyst study released earlier this year found that using green steel would increase infrastructure project costs by just 0.2-1.2%.
The final policy should commit to a GPP mandate with a clear start date and a phased increase in procurement targets, starting with a modest share of low-emission steel in selected central government projects. Incorporating the Ministry of Steel’s December 2024 green steel taxonomy into life-cycle costing would provide a ready basis for implementation. Over time, combining public procurement with longer-term offtake commitments could help build a reliable market for low-carbon steel.
Energy and raw material security and growth are legitimate priorities for a country that will need far more steel. But, as the Roadmap showed, these objectives can be pursued alongside decarbonisation. With its competitive advantage in low-cost renewable energy and green hydrogen, India has an opportunity to build a globally competitive green steel industry. The final policy could bring these priorities together and commit to a Green Steel Mission (which the government announced in 2024 but scrapped later) that supports the sector’s transition while securing its long-term competitiveness.
(The views expressed are personal)
This article is authored by Nandan Sharalaya, head of programme, Kinshu Dang, senior manager - networks and partnerships and Sakshi Balani, director, India at Climate Catalyst.


