E-Paper


UPI AutoPay: Will you now pay extra for OTT, SIP and bill payments? What new MDR rules say
UPI AutoPay payments for OTT subscriptions, bills and SIPs remain outside the new prescribed MDR framework. Here's what the latest rules mean for users.

 Prefer HTon Google


With the new Merchant Discount Rate (MDR) framework coming into effect for certain high-value UPI merchant payments, users may wonder whether recurring payments made through UPI AutoPay will also attract additional charges.
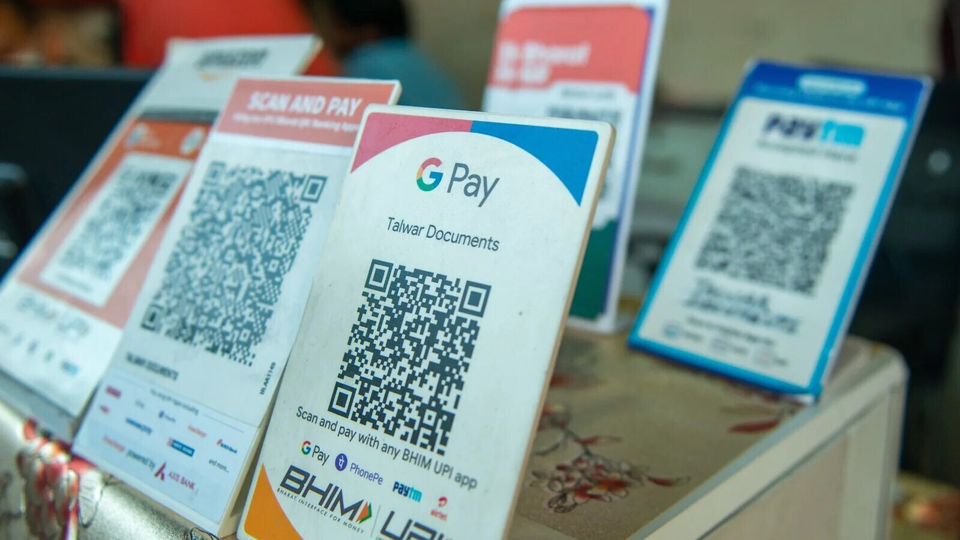
Automated recurring payments made through UPI mandates are not covered by the prescribed MDR framework, meaning payments such as utility bills, OTT subscriptions and mutual fund instalments will not attract the new 0.4% MDR merely because they exceed ₹2,000.
UPI AutoPay allows users to create an electronic mandate that authorises a merchant or service provider to automatically collect recurring payments from their linked bank account. It can be used for expenses including electricity and mobile bills, EMIs, insurance premiums, OTT subscriptions and mutual fund payments. NPCI describes AutoPay as a facility for recurring e-mandates through UPI-enabled apps.
Deep Dive

Also Read | UPI charges of 0.4% to be levied on merchant transactions above ₹2,000
The key distinction is between a regular UPI merchant payment and an automated recurring mandate. Under the new MDR framework, a 0.4% charge will apply to specified merchant transactions above ₹2,000, with the MDR paid within the payment ecosystem rather than by the customer. However, automated recurring payments are excluded from this new MDR framework.
For example, if a user has a ₹2,500 monthly OTT subscription and has authorised the payment through UPI AutoPay, the amount is collected automatically under the existing mandate. The new MDR framework for specified high-value merchant UPI transactions does not mean that the user will suddenly have to pay an additional 0.4% simply because the recurring payment exceeds ₹2,000.
Similarly, a person paying ₹5,000 every month towards a mutual fund SIP through a UPI mandate can continue using the recurring payment facility without the new prescribed MDR being applied to the transaction.
Also Read | New UPI rules: What to know about person-to-person payments, monthly quota
The update therefore does not mean that every UPI payment above ₹2,000 will attract a fee. Person-to-person UPI payments remain free, while payments to merchants of up to ₹2,000 also remain outside the MDR framework. The government has said MDR will be borne within the merchant payment ecosystem and is not a charge imposed directly on customers.
Under the new rules, a 0.4% MDR will apply to eligible merchant transactions above ₹2,000. For transactions of ₹75,000 or more, the MDR will be capped at ₹300 per transaction.
Will customers have to pay the 0.4% charge?
No. The government has clarified that the MDR is not a charge on UPI users. Banks have been advised to ensure that merchants do not pass the MDR cost on to customers. UPI apps are also not allowed to impose platform fees or hidden charges on users because of the new MDR framework.
If you pay a merchant ₹5,000 through UPI, the new MDR does not mean you will automatically pay an additional ₹20.
Sending money to another person remains free
The new framework does not apply to person-to-person (P2P) UPI payments.
Whether you send ₹500 or ₹50,000 to another person, there will be no MDR or transaction charge. The government has specifically said P2P UPI payments will remain free regardless of the amount.