
 E-Paper


Nobel Prize in Economics is a message to Fed: Report
In Warsh’s view, the Fed can achieve the best results without explaining itself. But Woodford’s research shows that communication is key to achieving success.

 Prefer HTon Google


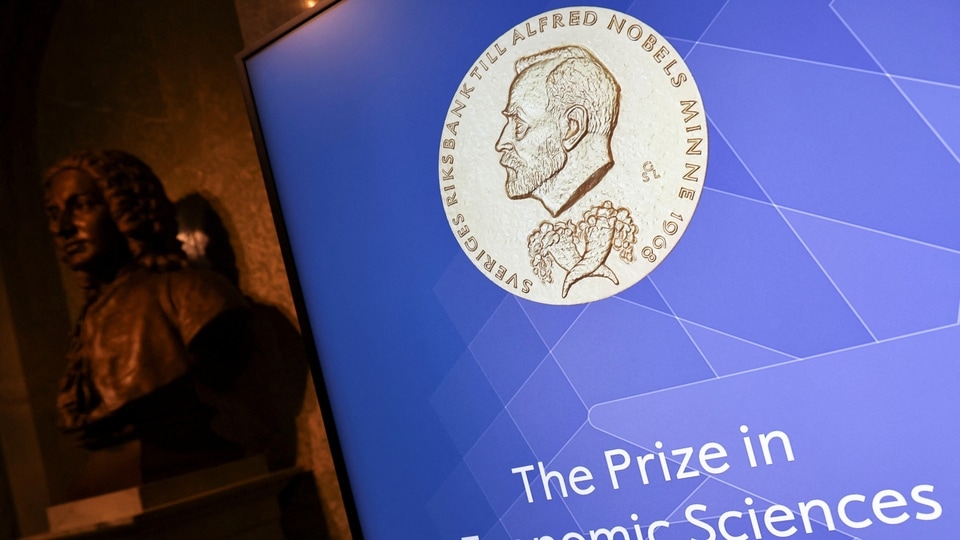
The Royal Swedish Academy of Sciences has a fantastic sense of humor. At a time when Federal Reserve Chair Kevin Warsh has turned central bank “forward guidance” into a banned phrase, the academy awarded the Nobel Prize in economics to Michael Woodford, one of the intellectual fathers of the practice, and Robert Hall, whose research on household expectations provided a foundation for Woodford’s later research. Hopefully, the award will lead Warsh to reconsider his crusade against guidance and transparency.
Ever since he was tapped to lead the Fed earlier this year, Warsh has been adamant about the idea that the central bank should “stop talking so much.” He has repeatedly declined to provide an explanation of what the interest rate-setting Federal Open Market Committee might do in response to changing economic conditions, or what is known as the Fed’s so-called reaction function. Also, he has slashed the size of the Fed’s post-monetary policy meeting statements; shortened press conferences; floated an idea to reduce the number of times the Fed meets annually and while taking a dim view of the Summary of Economic Projections, which is the Fed’s anonymous survey of policymakers on their rate and economic forecasts, declining to participate himself.
Deep Dive

In Warsh’s view, the Fed can achieve the best results without explaining itself. But Woodford’s research shows that communication is essential to achieving success. As he once put it in an interview, effective central banking depends not just on making the right call, but “communicating about how you make it also matters.” An effective communication strategy means that markets can immediately price in what policymakers are likely to do in response to a given macroeconomic development, helping reach a central bank’s intended results efficiently.
Woodford’s research in the 1990s and early 2000s established that policy works primarily through expectations, giving central bankers an economic rationale for opening institutions that had previously been viewed as temples of secrecy. His influential 2003 paper with economist Gauti Eggertsson is often credited with providing an intellectual basis for the first explicit Fed use of guidance on the path of monetary policy under then Chair Alan Greenspan. That year, Greenspan and the FOMC had already slashed the target federal funds rate to 1%, but 10-year yields weren’t responding in kind. So when they convened in August, the Fed held rates but added a sentence noting that the FOMC believed that “policy accommodation can be maintained for a considerable period.”
It was a revolutionary sentence that Hall’s work on household expectations and Woodford’s on Fed communication made possible. As Woodford wrote in a later paper presented at the Federal Reserve Bank of Kansas City’s Jackson Hole Economic Policy Symposium in 2005, the transparency revolution brought broad benefits:
There is every reason to believe that this has been beneficial, not only from the point of view of reducing the uncertainty with which traders and other economic decisionmakers must contend, but also from that of enhancing the accuracy with which the FOMC is able to achieve the effects on the economy that it desires, by keeping the expectations of market participants more closely synchronized with its own.
When the Fed slashed rates to near-zero during the global financial crisis, the Fed under Chair Ben S. Bernanke — an occasional Woodford co-author — started using forward guidance much more actively to provide additional easing of financial conditions that policy rates alone couldn’t provide, limited by the zero lower bound.
In August 2011, the committee said economic conditions were “likely to warrant exceptionally low levels for the federal funds rate at least through mid-2013.” For his part, Woodford said he had reservations about the specific form of that guidance. He said it was filled with “fine print” that gave the committee escape hatches, and preferred other “target criterion,” proposing at Jackson Hole in 2012 that the Fed consider a nominal GDP target. Although the Fed didn’t take his nominal GDP suggestion exactly, it did moved toward a target threshold in December 20212.
Also Read | The research associates who help scientists on their Nobel journey
With inflation above the Fed’s 2% target for six years running now, the challenges facing monetary policy today are vastly different today from those during the financial crisis, and that means guidance about the future should take a different shape.
The Summary of Economic Projections — which is often used to signal the direction of monetary policy — remains important, but it may have to be augmented and improved as part of a series of institutional reviews underway. For instance, the public often places too much focus on the median projection in the document, but that statistic doesn’t necessarily represent a consensus view of policymakers. A better idea might be to link individual policymakers’ rate projections with their economic forecasts, so that users can infer how each policymaker is thinking about making policy decisions under a set of macroeconomic assumptions. The introduction of scenario analysis would also help the public understand central bankers’ thinking.
Beyond the pure economic justification, transparency is about institutional survival. Time and again, central bank opacity has made the institutions targets of a skeptical public and opportunistic populists. Crucially, the Fed has protected itself — and its ability to set set interest rates to the long-term benefit of the American people — by opening itself up to the world. An open Fed is a more credible Fed that will find stronger societal support at a time when its institutional integrity is under attack by President Donald Trump.
Today’s economy and politics demand just as much communication with the public as was the case when Woodford’s research helped popularize guidance. And arguably, we need that transparency more than ever.


